To calculate luggage manufacturing cost, sum material, labor, overhead, and tooling costs, then divide by unit volume. This method provides a clear cost breakdown for accurate luggage pricing decisions.
- A reliable cost model separates direct materials from labor and overhead.
- Tooling and setup costs must be amortized across the expected order volume.
- Freight and duty should be included when calculating landed cost.
- Regular audits of factory quotes prevent margin erosion.
Why a Standardized Cost Model Matters
Luggage buyers often face quotes that fluctuate without clear justification. A standardized model removes guesswork. It isolates the variables that actually drive price.
The result is a defensible number. You can compare suppliers, negotiate terms, and protect margins. The process requires basic accounting logic and a firm understanding of the product build.
This guide walks through the calculation. It covers every major cost center. It explains why each step is necessary.
What Data Do You Need Before Starting
Before you calculate anything, you need a Bill of Materials. This document lists every component in the finished product.
For luggage, this includes the main shell, lining fabric, zippers, handles, wheels, and fasteners. You need the unit weight of each item. You also need the factory’s unit price for each.
Labor data is equally critical. You need the standard hours per operation. This includes cutting, sewing, assembly, and quality inspection. You need the hourly wage rate. It should reflect the factory’s actual rate, including statutory benefits.
You also need to know the expected order quantity. This number drives the amortization of tooling costs. A small order spreads fixed costs differently than a large one.
Step 1: Calculate Direct Material Costs
Start with the most visible costs. Multiply the unit price of each component by the quantity used per bag.
For a rolling suitcase, this means calculating the cost of the shell, the lining, the zippered pockets, the telescopic handle, and the four wheels. Include the small items. The rivets, the feet, and the brand labels.
Sum these values. This gives you the total direct material cost per unit.
A common mistake is ignoring the scrap factor. Factories need extra material to account for defects and cutting loss. Add a percentage to your material cost. A standard allowance covers these losses. This brings your number closer to reality.
Step 2: Calculate Direct Labor Costs
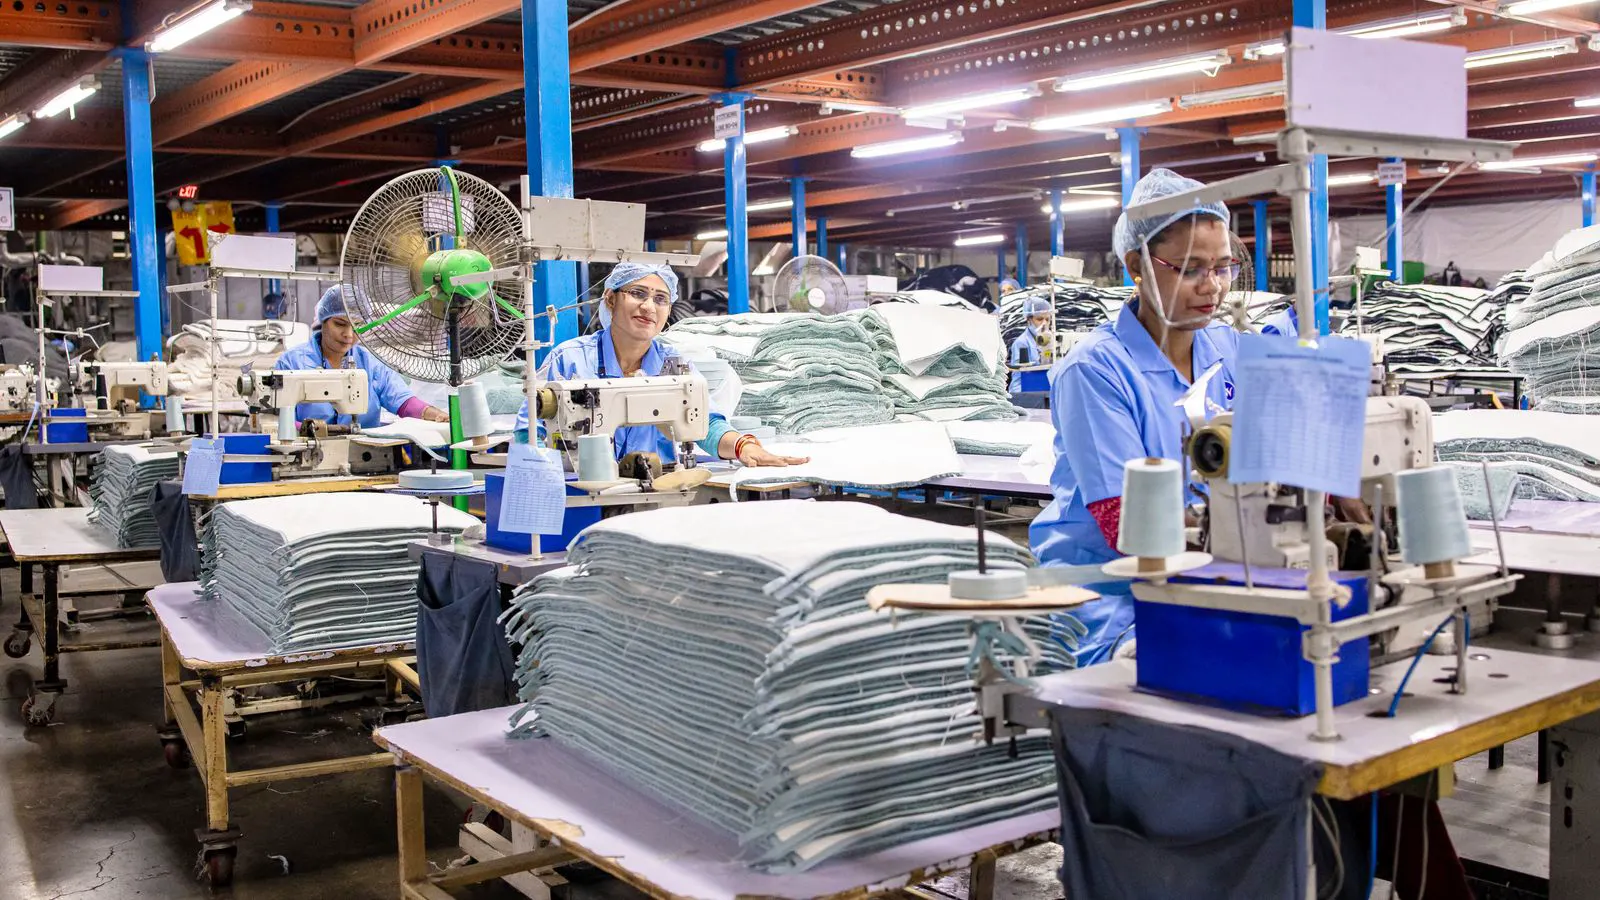
Next, estimate the labor time required for each stage. Break the process down. Cutting takes time. Sewing takes time. Assembly takes time. Quality control takes time.
Multiply the hours per stage by the hourly wage rate. Sum the results. This is your direct labor cost.
This step requires accurate time studies. If the factory estimates assembly at four hours, verify that number. Ask for a breakdown. Ask to see the standard operating procedures.
Labor costs vary by region. A factory in one country may charge half the rate of another. This difference can shift your total cost significantly. Always use the specific factory’s rate. Do not use a national average.
Step 3: Assign Overhead and Indirect Costs
Overhead covers costs that are not directly tied to a single unit. These include factory rent, electricity, maintenance, and management salaries.
Most factories apply overhead as a percentage of labor cost. Some use a percentage of direct materials. Ask the supplier which method they use.
If you are calculating the cost yourself, you need an estimate. A general rule of thumb helps here. Apply a reasonable percentage to your direct labor cost. This percentage must cover the factory’s operating expenses.
Do not skip this step. Overhead is often the largest hidden cost. Ignoring it leads to underpricing. You may end up with a quote that looks attractive but leaves no profit.
Step 4: Amortize Tooling and Setup Costs
Tooling costs are fixed. They do not change with volume. They are incurred once at the start of production.
For luggage, tooling includes molds for hard shells, stamps for soft goods, and special fixtures. A new hard-shell mold can be expensive. It must be spread across the expected units.
Divide the total tooling cost by the number of units in the first order. This gives you the per-unit tooling cost.
If you plan to reorder, the tooling cost drops per unit. This is why larger orders often have a lower unit price. The fixed cost is diluted.
A common mistake is forgetting that tooling may need updating. If the design changes, new tools may be required. Factor in a contingency.
Step 5: Add Quality Control and Packaging
Quality control is a separate line item. It covers inspection, testing, and documentation.
For luggage, this includes pressure testing the zippers, checking wheel durability, and verifying the shell integrity. You also need to budget for packaging. Boxes, corner guards, and labels all add cost.
Packaging must be robust. It protects the product during transit. A damaged bag arrives with a negative review. The cost of packaging is small compared to the cost of a return.
Calculate the cost of one box and one set of protective materials. Add it to your unit total.
Step 6: Include Freight and Duty
Your cost is not complete until the bag reaches your warehouse. Freight and duty are part of the landed cost.
Freight depends on the origin, destination, and transport method. Air freight is fast but expensive. Sea freight is slow but cheaper.
Duty depends on the Harmonized System code and the value of the shipment. You need a clear estimate here.
Add these costs to your per-unit calculation. Divide the total freight and duty by the number of units.
This step is often overlooked. It can add a significant percentage to your total cost. If you ignore it, you will not know your true profit margin.
Step 7: Add a Profit Margin
Finally, add your target profit margin. This is the amount you keep after paying the factory.
Choose a percentage that reflects your market position. A premium brand may require a higher margin. A budget brand may operate on thinner margins.
Multiply your total cost by one plus your margin percentage. This gives you your target selling price.
Do not skip this step. A cost calculation without a margin is just an expense report. It does not tell you if the business is viable.
Common Mistakes to Avoid
Buyers make predictable errors in this process.
The first mistake is using outdated material prices. Material costs fluctuate. Plastics, fabrics, and metals change in price. Use current quotes from the factory.
The second mistake is assuming labor efficiency. Factories have different skill levels. A less experienced team takes longer. This increases labor cost per unit.
The third mistake is ignoring hidden fees. Some factories add “miscellaneous charges.” These cover inspection, storage, or special handling. Ask for a line-item breakdown.
The fourth mistake is not validating the quantity. If you order 500 units, the tooling cost per unit is high. If you order 5,000, it is low. Make sure your quantity is realistic.
How to Verify Your Calculation
Once you have your number, verify it.
Request a detailed cost breakdown from the factory. Compare your lines to theirs. Look for discrepancies. Ask for explanations.
If the numbers do not match, dig deeper. Ask for the labor time studies. Ask for the material supplier quotes. Ask for the overhead rate.
A transparent factory will provide this information. A vague factory will not. This is a red flag.
Run the calculation again with slightly different assumptions. What happens if material costs rise by ten percent? What happens if labor time increases by ten minutes?
This stress test helps you prepare for changes. It shows you where your margin is most vulnerable.
Final Thoughts
Calculating manufacturing cost is a discipline. It requires accuracy and diligence.
Use this method to build a reliable model. It gives you control over your pricing. It helps you make informed decisions.
A clear cost breakdown protects your business. It keeps you competitive. It ensures you are not paying for what you do not need.
Start with your Bill of Materials. Build your model step by step. Verify your numbers. Adjust as needed.
The result is a solid foundation for your purchasing strategy.
Frequently asked questions
How often should I update my cost calculation?
Update the model every time material prices change or after each production run. This ensures your numbers reflect current market conditions.
Can I use a standard overhead percentage?
Yes, but verify it with the specific factory. Overhead rates vary by location and factory size. Ask for their actual rate.
Do I need to include freight in the unit cost?
Yes. Freight and duty are part of the total cost of goods. Excluding them leads to an inaccurate profit margin.
How do I handle tooling costs for small orders?
Amortize the tooling cost across the first order. If the order is small, the per-unit tooling cost will be high.
What is the best way to verify factory quotes?
Request a detailed line-item breakdown. Compare it to your own calculation. Ask for supporting documents like material quotes and labor studies.